Data & method
- Source
- investor activity tracked by VCInfo (round amounts: Fundup)
- Period
- 2025-11-14 to 2026-11-12
- Method
- Source: investor activity tracked by VCInfo (round amounts: Fundup). Period: 2025-11-14 to 2026-11-12. Sample: 480 records. VCinfo compiles investor activity from firm websites and portfolio pages, regulatory filings (Form D, UK registers) and news. It does not see every fund or every investment, and portfolio changes are picked up with a delay. Round amounts come from Fundup. Recent months are provisional because late reports keep arriving; compare with care. Figures for the most recent period are provisional and will rise as late reports arrive.
How VCinfo collects its data and what it can miss: Methodology.
The five most active corporate VCs of the earlier half-year logged 77 participations in the latest six months against 79 before, while the other 20 corporate investors in our data rose from 128 to 196, a 53% increase. The headline growth in corporate venture activity that VCinfo tracked came almost entirely from outside the previous leadership group.
This cut covers 25 corporate venture investors and 480 tracked participations between 2025-11-14 and 2026-11-12, split into the most recent six months (273) and the six months before (207), a rise of 31.9%. The recent window is provisional: late reports keep arriving, so recent counts will rise.
The previous top five were flat as a group
In the earlier six months the five most active corporate investors in our data were Salesforce Ventures (21), J.P. Morgan Growth Equity Partners (16), Citi Ventures (14), CapitalG (14) and M12 (14). Together they accounted for 79 of 207 participations, or 38.2%.
In the recent six months the same five logged 77. Salesforce Ventures added 7 and Citi Ventures added 1, but J.P. Morgan Growth Equity Partners slipped by 1, CapitalG by 3 and M12 by 6. Their combined share of tracked participations fell to 28.2%.
| Group (fixed membership) | Prior 6 months | Recent 6 months | Change |
|---|---|---|---|
| Prior top five | 79 | 77 | -2.5% |
| Other 20 firms | 128 | 196 | +53.1% |
| All 25 firms | 207 | 273 | +31.9% |
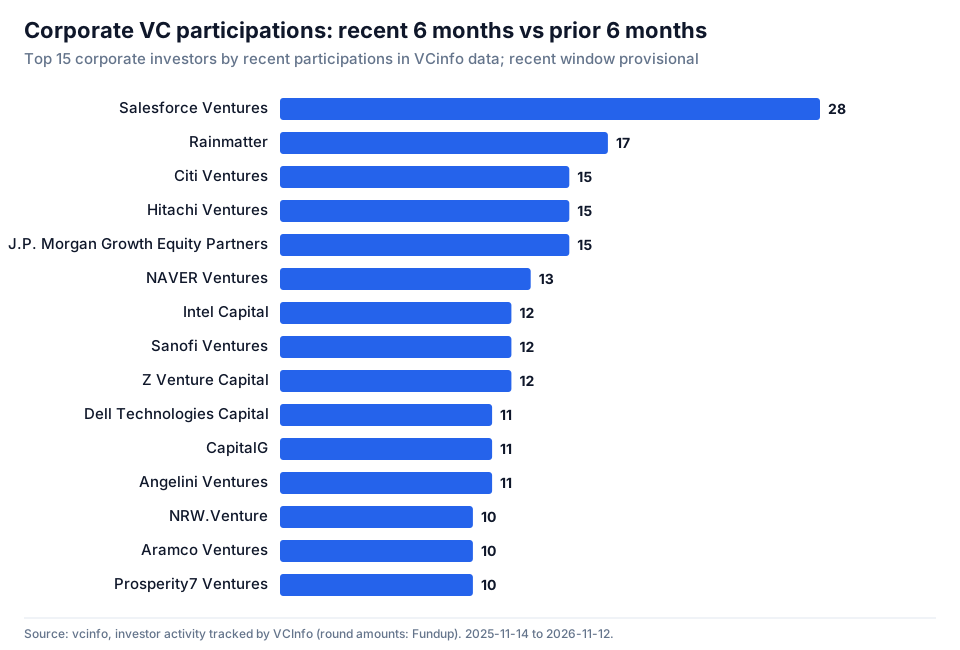
The recent leaderboard is also less concentrated. The recent top five (Salesforce Ventures 28, Rainmatter 17, and Citi Ventures, Hitachi Ventures and J.P. Morgan Growth Equity Partners at 15 each) account for 90 of 273 participations, 33.0%, against 38.2% for the prior top five.
15 firms grew, 4 held flat, 6 declined
The split by direction shows how broad the increase was among the investors we track.
| Direction | Firms | Prior | Recent | Net change |
|---|---|---|---|---|
| Increased | 15 | 104 | 186 | +82 |
| Unchanged | 4 | 33 | 33 | 0 |
| Decreased | 6 | 70 | 54 | -16 |
The 15 growing firms added 82 participations, more than the net gain of 66 across the full group. The six decliners shed 16. Sanofi Ventures (12), Databricks Ventures (7), EBRD Venture Capital (7) and LG Technology Ventures (7) recorded identical counts in both windows.
Where the growth sits: Hitachi, NAVER, Z Venture Capital, Dell, Aramco
The largest absolute gains in our data came from firms that were mid-table or lower in the earlier period:
| Firm | Prior | Recent | Change % |
|---|---|---|---|
| Hitachi Ventures | 5 | 15 | 200 |
| Angelini Ventures | 1 | 11 | 1000 |
| Salesforce Ventures | 21 | 28 | 33.3 |
| NAVER Ventures | 6 | 13 | 116.7 |
| Rainmatter | 10 | 17 | 70 |
| Z Venture Capital | 5 | 12 | 140 |
| Dell Technologies Capital | 4 | 11 | 175 |
| Aramco Ventures | 4 | 10 | 150 |
| NTT DOCOMO Ventures | 3 | 8 | 166.7 |
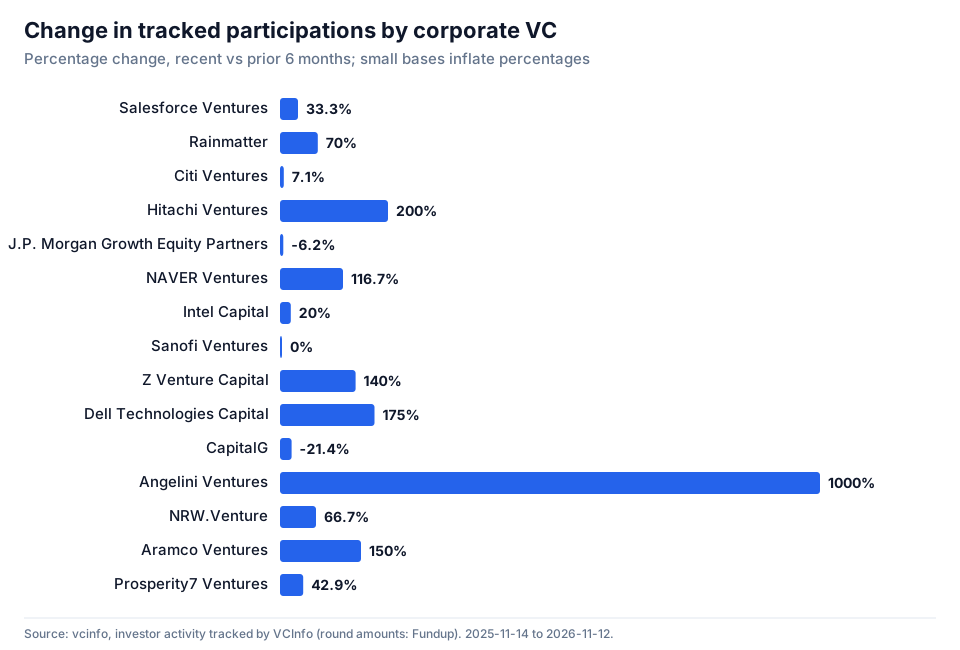
Hitachi Ventures tripled from 5 to 15 and now sits level with Citi Ventures and J.P. Morgan Growth Equity Partners. Rainmatter moved into second place with 17. Angelini Ventures went from 1 to 11; the 1,000% figure reflects a small base, and the absolute count is the more useful signal.
Two clusters stand out. Corporate investors with parents headquartered in Japan or South Korea (Hitachi Ventures, NAVER Ventures, Z Venture Capital, NTT DOCOMO Ventures, Samsung NEXT, Sony Innovation Fund, Toyota Ventures, LG Technology Ventures) rose from 49 to 76 participations combined, up 55.1%. That growth was uneven inside the group: Hitachi, NAVER, Z Venture Capital and NTT DOCOMO Ventures rose sharply, while Sony Innovation Fund and Toyota Ventures declined.
Aramco Ventures and Prosperity7 Ventures together went from 11 to 20 tracked participations.
The decliners are mostly large US tech and hardware names
The six firms with fewer tracked participations were J.P. Morgan Growth Equity Partners (16 to 15), CapitalG (14 to 11), M12 (14 to 8), Toyota Ventures (10 to 7), Sony Innovation Fund (8 to 7) and Qualcomm Ventures (8 to 6). Combined they fell from 70 to 54, down 22.9%.
M12 had the largest drop in absolute and relative terms in our data, down 6 participations, or 42.9%. Within semiconductors and hardware the picture is split: Dell Technologies Capital rose from 4 to 11 and Intel Capital from 10 to 12, while Qualcomm Ventures fell from 8 to 6.
These counts describe participations VCinfo has recorded. A lower count is not evidence that a firm slowed its investing overall; it may also reflect portfolio-page updates that have not yet been captured, which the provisional status of the recent window makes more likely.
What this means
Interpretation, based on the 25 corporate investors in this cut and subject to late-arriving data:
- For founders building a CVC target list: the most active names of the earlier period are not the ones adding volume. In our data, Hitachi Ventures, NAVER Ventures, Z Venture Capital, Dell Technologies Capital and Aramco Ventures each more than doubled their tracked participations, while M12 and CapitalG recorded fewer. If our coverage is representative, the pool of corporates actively writing cheques is widening rather than deepening at the top.
- For investors and platform teams sourcing co-investors: Salesforce Ventures remains the most active corporate investor in the rounds we track, with 28 participations. Beyond it, the second tier has reshuffled, with Rainmatter, Hitachi Ventures and NAVER Ventures now ahead of CapitalG and M12.
- For analysts: the 31.9% aggregate rise is better read as a breadth story than a leader story. The previous top five accounted for a smaller share of activity (28.2% vs 38.2%), and the gain from 15 growing firms (82 participations) exceeds the net group gain (66). Because the recent window is provisional, its counts are more likely to rise than fall as reports arrive.
VCinfo users can follow these 25 corporate investors' participations and co-investors as late reports update the recent window.
Questions
How much did corporate VC participations change in VCinfo's data?
Across the 25 corporate venture investors in this cut, participations rose from 207 in the earlier six months to 273 in the most recent six months, a 31.9% increase. Recent figures are provisional and will rise as late reports arrive.
Which corporate VC was most active in the last six months?
Salesforce Ventures, with 28 participations in the rounds VCinfo tracks, up from 21 in the prior six months. Rainmatter followed with 17.
Which corporate VCs recorded fewer participations?
Six of the 25 recorded fewer participations: M12 (14 to 8), CapitalG (14 to 11), Toyota Ventures (10 to 7), Qualcomm Ventures (8 to 6), Sony Innovation Fund (8 to 7) and J.P. Morgan Growth Equity Partners (16 to 15). This reflects tracked activity only, not their full deal flow.
Is the Angelini Ventures 1,000% increase meaningful?
It reflects a move from 1 to 11 tracked participations. The percentage is large because the base is small; the absolute count of 11 is the more useful figure.
Prepared with AI assistance from vcinfo data; reviewed by the vcinfo team.